Earning extra revenue from freelancing, digital products, or affiliate marketing is only the first half of personal finance. How you allocate that surplus determines whether your money loses purchasing power to inflation or compounds steadily over time.
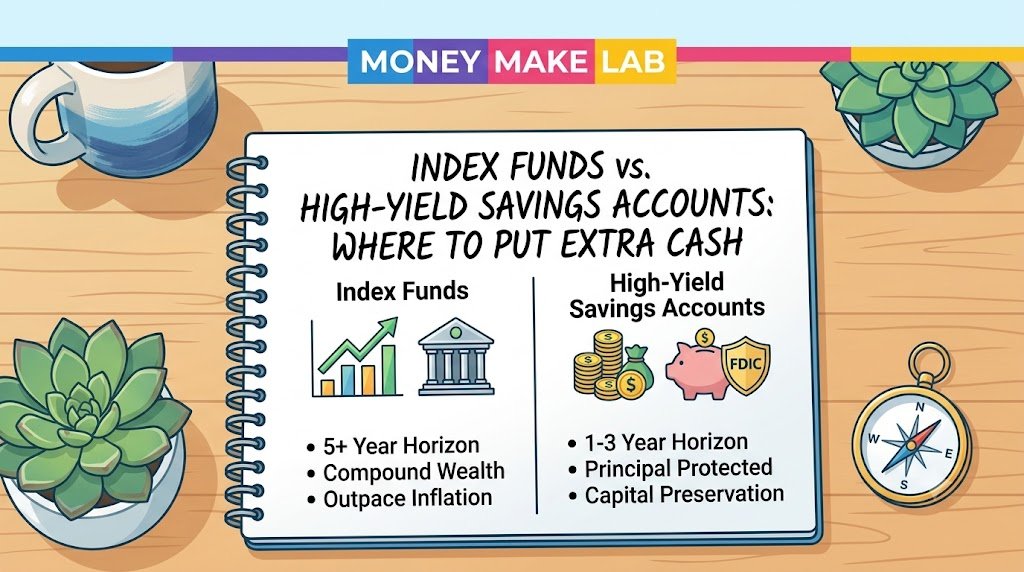
Beginners often pit High-Yield Savings Accounts (HYSAs) against Index Funds as an “either/or” decision. In reality, they are two complementary tools designed for entirely different financial timelines and risk profiles.
Comparing the Core Mechanics
| Feature | High-Yield Savings Account (HYSA) | Broad-Market Index Funds (e.g., S&P 500 / Total Stock) |
|---|---|---|
| Risk to Principal | Zero risk up to $250k (FDIC/NCUA Insured) | Market risk; value fluctuates daily in the short term |
| Historical Return | Tied to Federal Reserve rates (variable APY) | Historically ~7–10% average annual return (not guaranteed) |
| Liquidity | Immediate (transfers take 1–2 business days) | High liquidity, but selling during down markets locks in losses |
| Optimal Time Horizon | Short-term (0–3 years) | Long-term (5–10+ years) |
When to Prioritize a High-Yield Savings Account
A High-Yield Savings Account functions as capital preservation. Brick-and-mortar traditional banks often pay negligible interest (often 0.01% APY), whereas online HYSAs (such as Marcus by Goldman Sachs, Ally, or Capital One 360) pass along higher interest yields backed by full federal deposit insurance.
- Emergency Funds: A reserve of 3 to 6 months’ worth of essential living expenses. This money must be immune to stock market drawdowns.
- Short-Term Purchase Targets: Savings allocated for a home down payment, wedding, car purchase, or planned tax payments within the next 24 months.
When to Invest in Broad-Market Index Funds
While an HYSA protects your nominal dollar balance, it frequently lags real-world inflation over multi-decade spans. Index funds (such as low-cost ETFs tracking the S&P 500 or Total US Stock Market via Vanguard, Fidelity, or Schwab) allow investors to purchase an entire basket of hundreds of profitable public companies in a single transaction.
- Compounding Engine: Reinvesting dividend payouts over long horizons leverages the power of compound interest.
- Tax-Advantaged Vehicles First: Prioritize deploying cash into accounts like a Roth IRA or workplace 401(k) before purchasing index funds within a taxable brokerage account.
- Dollar-Cost Averaging: Investing a consistent dollar amount every month eliminates the temptation to guess market timing.